Area Guide
Best Investment Opportunities Near Dwarka Expressway (2026)
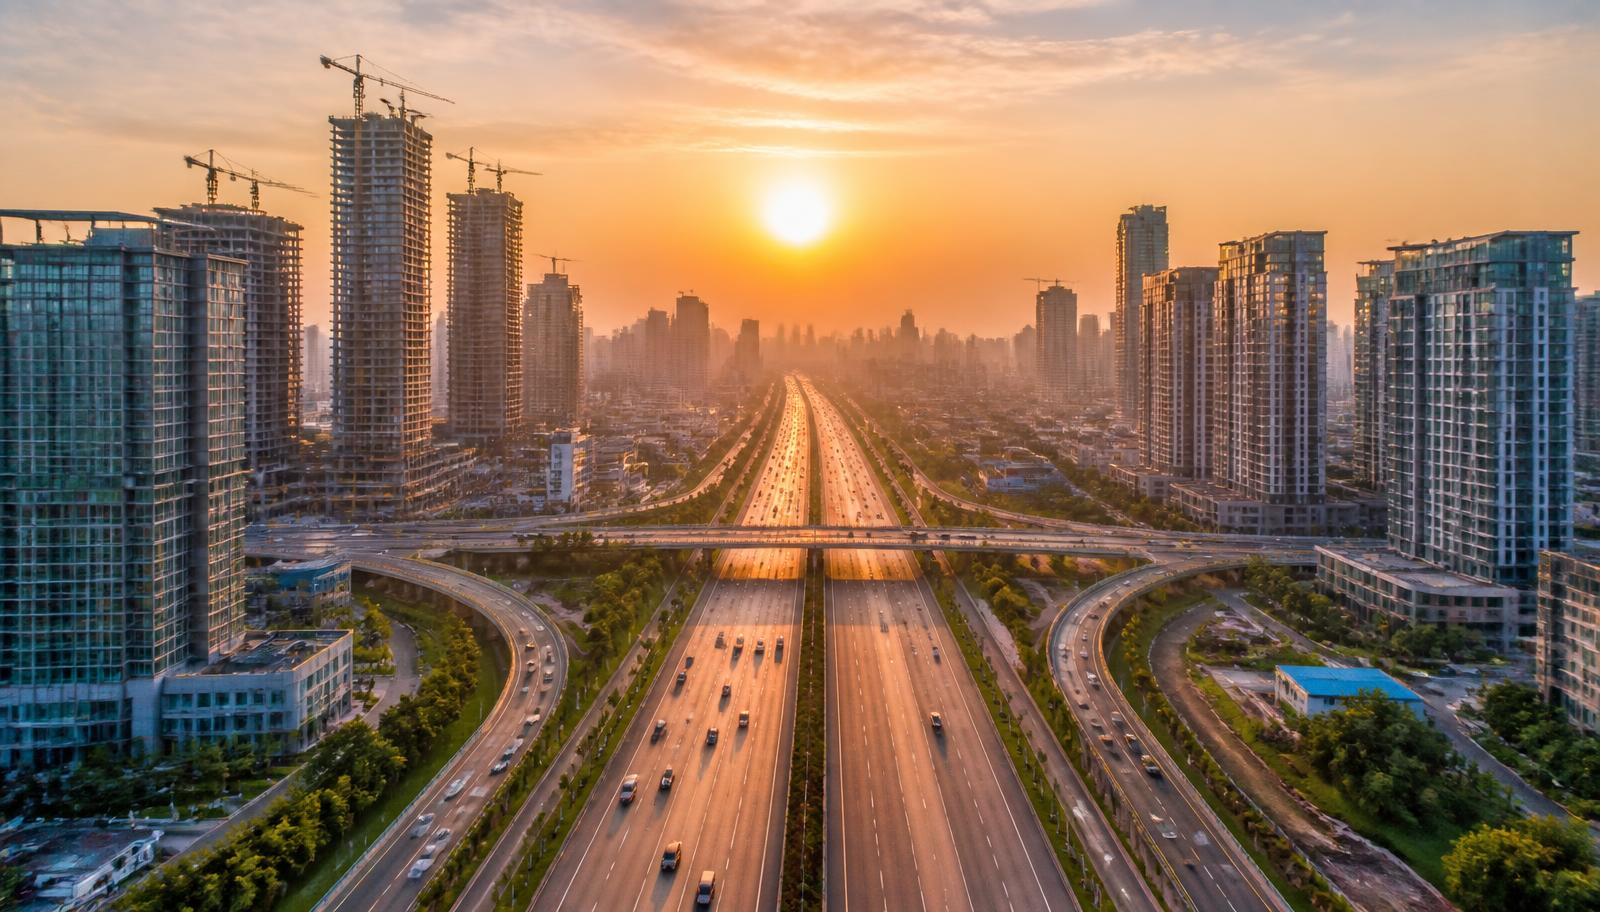
Dwarka Expressway is now fully operational. Here's the investor's playbook — which sector, which project, what price and when to exit.
The infrastructure story
29 km, 8-lane, 16 flyovers, 4 underpasses, direct IGI Airport connectivity via Shiv Murti. Toll-free for cars. Cuts Dwarka-Manesar to 25 minutes.
Best sectors to buy
Sector 113 (entry to Delhi), Sector 102–103 (Godrej, Signature Global belt), Sector 106–109 (Elan, Sobha), Sector 111 (Smartworld), Sector 37D (Krisumi belt).
Expected appreciation
12–18% CAGR over 3 years as more projects hit possession and rental demand from Dwarka Sector 21 metro + IGI catchment kicks in.
Rental outlook
3-BHK monthly rental ₹45,000–75,000 today; expected to touch ₹65,000–95,000 by 2028.
When to exit
Hold minimum 3 years to cover STCG-to-LTCG shift. Ideal exit window: after OC + rental stabilisation, before the next launch wave dilutes resale demand.
Sector-by-sector entry points
Sectors 102–106 sit closest to the Delhi border with the shortest airport drive and the highest current pricing on the corridor. Sectors 108–113 offer larger unit sizes and a growing school cluster. Sectors 88–95 connect to New Gurgaon and the SPR interchange with the lowest entry pricing and the longest runway. Sector 99–101 is the retail and mixed-use spine. Match the sector to whether you value airport access, family infrastructure or entry price.
The office and retail pipeline that drives rents
The corridor's investment case rests on commercial delivery — millions of square feet of Grade-A office and organised retail are in various stages of construction across Sectors 88A, 99, 102 and 111. Rental demand on the expressway tracks office occupancy with a 12–18 month lag, so residential yields here should improve materially as these campuses reach stabilised occupancy.
Risk factors to underwrite honestly
Three real risks: concentration of simultaneous supply across many towers, which can cap short-term price growth; social infrastructure arriving slower than brochures imply; and metro extension timelines slipping. None of these break the long-term case, but they do mean the corridor rewards a 4–6 year horizon rather than a 24-month flip.
How to structure the buy
Prefer projects with completed structures or advanced construction over new launches if you want a shorter path to rent. Prefer 3 BHK sizes between 1,800 and 2,400 sqft — the deepest resale band. Insist on possession-linked or construction-linked plans, and negotiate on PLC and club charges rather than on headline rate.
The role of Sector 21 Dwarka metro and last-mile connectivity
The Dwarka Sector 21 metro station sits at the Delhi end of the expressway and is the single biggest catchment driver for the corridor's residential demand, since it links directly into the Delhi Airport Express Line, cutting the commute for professionals working near IGI Airport, Aerocity and central Delhi to under 30 minutes from several upcoming sectors. Last-mile connectivity from individual sectors to this station currently relies on private vehicles and app-based cabs, since dedicated feeder bus services are still being scaled up; buyers evaluating a purchase purely for rental demand from young professionals should weigh a sector's actual drive time to the nearest metro-linked point, not just its straight-line distance on a map, since internal sector roads and ongoing construction traffic can add 10–15 minutes during peak hours.
How social infrastructure is catching up on the corridor
Several international and CBSE-affiliated schools have opened or announced campuses along the expressway corridor in Sectors 106, 109 and 113, alongside multi-specialty hospital chains establishing satellite facilities to serve the growing resident base. This lag between residential possession and social infrastructure completion is normal in a fast-scaling corridor and typically closes within three to five years of a critical mass of families moving in. For end-users buying today, it is worth checking specifically which schools and hospitals are operational versus merely announced, since brochures for under-construction residential projects often list nearby social infrastructure that is itself still years from opening.
Comparing developer track records specific to this corridor
Not every developer active on Dwarka Expressway has an equally strong delivery record on this specific corridor, even if their reputation elsewhere in Gurgaon is solid — corridor-specific execution depends on local land aggregation, approvals timelines with the specific sector's DTCP office, and construction logistics given the ongoing roadworks. Buyers should specifically ask each shortlisted developer for their delivery history on Dwarka Expressway projects alone, rather than relying on their broader citywide reputation, since some developers have delivered flagship projects elsewhere years ahead of schedule while their expressway-corridor project has faced land or approval delays.
Group housing versus SCO and plotted options on the corridor
Beyond apartments, the corridor also offers licensed plotted development and SCO commercial plots in sectors like 88, 95 and 99, giving investors a choice between vertical group-housing exposure and horizontal land-linked exposure. Plotted development on this corridor has historically shown strong appreciation once basic infrastructure like roads and sewerage are commissioned by the developer, because land value appreciates independently of construction cost inflation. However, plotted purchases require more hands-on management — commissioning your own construction, managing security until the colony matures — compared to the turnkey nature of an apartment purchase.
Rental demand drivers beyond the airport catchment
While IGI Airport proximity gets most of the attention, a second, less discussed rental demand driver on this corridor is the growing cluster of corporate offices in adjacent Udyog Vihar, Sector 18 and the upcoming commercial development within the expressway sectors themselves, which will create a live-work-play dynamic reducing residents' dependence on a long commute to Cyber City or Golf Course Road for employment. As these office campuses reach stabilised occupancy over the next several years, rental demand from tenants working locally rather than commuting is expected to become an increasingly significant share of total rental absorption on the corridor.
Comparing carpet area efficiency across expressway projects
Loading factors on Dwarka Expressway projects have varied noticeably by developer, with some newer launches offering loading in the 28–32% range while a few older or more amenity-heavy projects run loading above 38%. Since most projects on this corridor are still under construction or recently delivered, buyers have the advantage of comparing actual RERA-disclosed carpet area figures across multiple live projects rather than relying on estimates, and this comparison often reveals meaningfully different effective ₹/sqft-of-carpet-area costs even among projects quoting similar headline super-area rates.
Assessing construction quality mid-way through possession
For buyers considering a near-possession or recently-delivered project on the corridor, a mid-construction or post-possession site visit reveals more than any brochure: check for visible water seepage on external walls facing the monsoon-exposed side, inspect whether landscaping and internal roads shown in renderings have actually been laid, and speak with residents of already-possessed towers within the same project about lift wait times and water supply consistency. Corridor-wide construction activity from multiple adjacent projects can also create temporary dust and traffic disruption for a few years even after your own tower is complete, which is worth factoring into end-use decisions versus a pure rental-investment decision.
Verifying land acquisition and litigation history specific to expressway sectors
A meaningful share of the historical delay on Dwarka Expressway projects traced back to land acquisition and compensation litigation between the state and original landowners, some of which persisted even after individual project licences were granted. Before booking, buyers should ask the developer specifically whether the licensed land parcel for their project was ever subject to a compensation enhancement case or a stay order at the Punjab and Haryana High Court, since even a resolved historical dispute can leave residual title notations that a careful advocate should flag during due diligence. This corridor-specific check matters more here than in older, long-settled sectors like DLF Phase 1–5, where land title has been stable for decades.
A worked example comparing possession-linked entry across three sub-corridors
Consider three comparable 3 BHK units of roughly 2,000 sqft: one in Sector 102 near the Delhi border, one in Sector 109 mid-corridor, and one in Sector 88A closer to the SPR interchange. At similar construction stages, the Sector 102 unit typically commands a 12–18% premium over Sector 88A for equivalent specification, reflecting airport proximity, while Sector 109 sits roughly in between, benefiting from an established school cluster. An investor prioritising near-term rental yield should weigh Sector 102's shorter commute for airport and Aerocity-linked tenants against its higher entry price, while a buyer prioritising long-term capital appreciation on a lower base may find Sector 88A's connection to the broader New Gurgaon office pipeline more compelling over a five-to-seven year hold.
Escalation and remedy options for corridor-wide road and utility delays
Where a developer's possession is contingent on external infrastructure — a service road connection, a sewage trunk line, or a substation commissioning by HSVP or the Municipal Corporation — buyers should distinguish between delay caused by the builder's own construction pace, which is compensable under RERA delay-interest provisions, and delay caused by pending government infrastructure, which developers sometimes cite as a force majeure defence. HRERA has in several orders held that a builder cannot indefinitely defer possession citing external infrastructure unless that infrastructure was an explicit, named condition precedent in the buyer agreement, so buyers should check whether their agreement lists any such condition and, if a delay is being blamed on external works, request the builder's written correspondence with the relevant authority as evidence of the actual cause.
Financing nuance: loan sanctions against under-construction expressway inventory
Because a subset of expressway-corridor land parcels historically carried land-acquisition sensitivities, some public-sector banks apply extra scrutiny or a lower loan-to-value ratio to certain projects on this corridor compared to identical-value projects in more established micro-markets, even after a project's own HRERA registration and licence are in order. Buyers should get a pre-approval in principle from at least two lenders before booking, since a mismatch between the expected LTV and the actual sanctioned amount discovered only after booking can create last-minute funding gaps; private banks and larger HFCs have generally been more consistent than smaller cooperative or regional banks in underwriting this corridor uniformly.
Rental math for a near-possession unit versus a fresh launch on the same corridor
A near-possession unit renting out within 6–9 months of purchase captures rental income sooner but is bought at a higher per-sqft entry cost, while a fresh launch bought 3–4 years from possession is cheaper per sqft but carries an extended no-income holding period plus construction risk. Modelling both to a common seven-year horizon, the fresh launch typically produces a higher blended IRR if delivered on schedule, because the lower entry base amplifies both rental yield and appreciation from that point forward, but this advantage narrows or reverses entirely if the project slips by more than 18–24 months, since the extended zero-income period compounds against the buyer. This makes developer execution track record, not just entry price, the single most important variable in this comparison.
Frequently asked
- Is Dwarka Expressway a good investment in 2026?
- Yes, for investors with a four to six year horizon. The road is fully operational, office and retail supply is delivering, and residential pricing still trades at a 35–45% discount to comparable Golf Course Extension inventory.
- What is the entry price on Dwarka Expressway?
- Ready and near-ready 3 BHK inventory generally runs ₹1.8–2.6 Cr, with rates in the ₹12,500–17,000/sqft band depending on sector and developer.
- Will the metro come to Dwarka Expressway?
- A metro extension serving the corridor's sectors is in the approved-alignment stage. Treat it as upside rather than a certainty when underwriting your purchase.
- How close are Dwarka Expressway sectors to the Delhi Airport Express metro line?
- Sector 21 Dwarka metro connects directly to the Delhi Airport Express Line, and several expressway sectors are within a 15-20 minute drive of this station, though dedicated feeder transport is still developing.
- Are schools and hospitals available yet on Dwarka Expressway?
- Several are operational in sectors like 106, 109 and 113, but buyers should verify which specific facilities are functioning today versus merely announced for the future before assuming immediate access.
- Should I buy a plot or an apartment on Dwarka Expressway?
- Plots offer land-linked appreciation and suit investors comfortable managing construction and interim security, while apartments offer a turnkey experience with immediate livability and broader financing options.
- Why do loading factors vary so much between Dwarka Expressway projects?
- Amenity-heavy projects and older launches often carry higher loading (38%+) than newer, more efficiency-focused launches (28-32%), so comparing RERA-disclosed carpet area is essential before judging true cost.
- Is construction noise and dust a long-term issue on this corridor?
- It is mostly a medium-term issue tied to the multiple simultaneous project launches on the corridor and should meaningfully reduce as more towers reach completion over the next several years.
- Should I check land litigation history before buying on Dwarka Expressway specifically?
- Yes, this corridor had more land-acquisition-related litigation historically than older Gurgaon sectors, so ask whether the licensed parcel faced any compensation enhancement case or court stay, even if resolved, and have an advocate check for residual title notations.
- Can a builder blame possession delay entirely on pending government road or utility work?
- Only if that specific infrastructure was named as a condition precedent in the buyer agreement; HRERA has held builders cannot indefinitely defer possession citing external works otherwise.
- Do banks treat loans on Dwarka Expressway projects differently from other corridors?
- Some public-sector banks apply extra scrutiny or slightly lower LTV to certain parcels given historical land sensitivities, so get pre-approval in principle from at least two lenders before booking.
- Is a near-possession unit or a fresh launch the better investment on this corridor?
- A fresh launch usually produces a higher blended return if delivered on time due to its lower entry base, but a delay beyond 18-24 months can erase that advantage, making developer execution track record the deciding factor.
Need a free 30-minute consultation on this?
Our senior advisors will help you shortlist projects, verify HRERA and structure your offer.